Egypt’s hospitality sector is witnessing growing investor confidence, with 97% of investors expressing optimism about the market’s prospects over the next three to five years, while 86% expect Revenue per Available Room (RevPAR) to increase, according to the HVS Egypt Hospitality Investment Pulse 2026 report.
The report, issued by HVS, a leading hospitality consultancy specializing in the Middle East and Africa, in collaboration with Future Hospitality Summit Egypt (FHS Egypt), revealed that none of the surveyed investors held a negative outlook on hospitality investment in Egypt.
Based on a survey conducted between September and October 2026 among hotel owners, developers, investors and financing institutions, the findings highlight a significant shift in investment priorities. Rather than questioning the strength of tourism demand, investors are increasingly focused on securing financing, managing foreign currency risks and turning investment opportunities into viable projects.
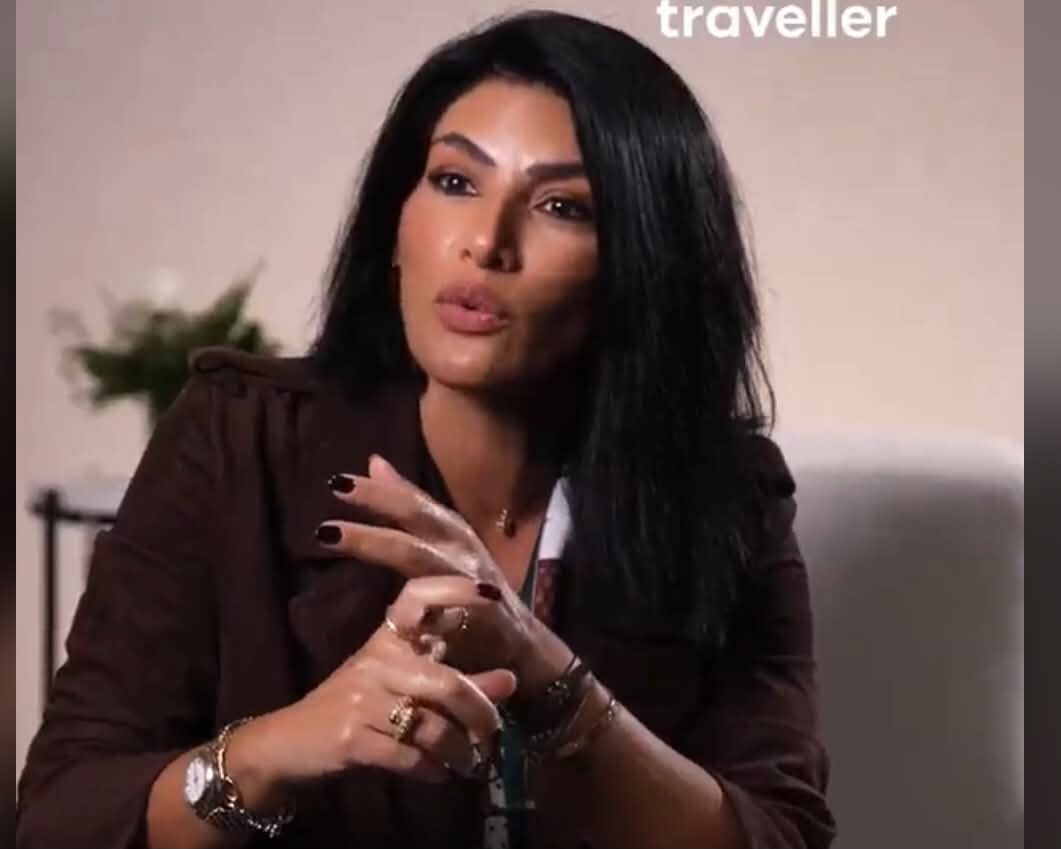
Hala Matar Choufany, President of HVS Middle East and Africa, said the findings demonstrate that confidence in Egypt’s tourism demand is no longer the main concern for investors.
She explained that attention has shifted toward investment execution, improving international air connectivity, developing human capital and enhancing operational efficiency.
Choufany added that the next phase of growth will depend on the market’s ability to translate investor confidence into actual investments by addressing financing constraints and foreign currency availability.
Gulf Investors to Lead Egypt’s Next Hospitality Investment Wave
Investors from Gulf Cooperation Council (GCC) countries are expected to lead the next wave of hospitality investment in Egypt over the coming five years, accounting for 45% of respondents, according to the HVS report.
Egyptian private-sector investors ranked second at 19%, followed by hotel operators and strategic partners at 16%, while international investment institutions accounted for 10%.
The findings reinforce expectations of continued investment inflows from Gulf markets, highlighting their growing role in financing hotel developments and expanding Egypt’s hospitality infrastructure.
Meanwhile, foreign exchange volatility emerged as the leading investment concern, cited by 32% of respondents, followed by regional geopolitical risks at 29%.
The report emphasized that investment challenges are increasingly associated with capital availability, foreign currency exposure and access to equity and debt financing, rather than insufficient tourism demand.
Capital-related constraints collectively accounted for more than half of respondents’ answers, highlighting the importance of financial stability and flexible funding structures in determining the feasibility of hospitality projects.
North Coast and Greater Cairo Lead Hotel Investment Destinations
Egypt’s coastal destinations are attracting the strongest investor interest, accounting for 61% of respondents’ preferences, with the North Coast emerging as the leading destination at 39%.
Greater Cairo and Giza followed closely, attracting 35% of investor interest, reflecting the continued appeal of major urban centers as gateways for international visitors and business travelers.
The findings also highlight growing interest in integrated developments that combine hotels, branded residences, commercial facilities, residential communities and entertainment services.
In terms of investment categories, branded residences and mixed-use developments ranked first, accounting for 32% of respondents’ preferences.
New hotel developments came second at 19%, while hotel conversions and rebranding projects, alongside renovation and repositioning initiatives, each accounted for 10%.
Another 29% of respondents identified investment opportunities across all these categories, indicating that Egypt’s hospitality growth potential extends beyond new hotel construction to include upgrading existing properties and improving their operational and financial performance.
Coastal and Leisure Tourism Expected to Drive Egypt’s Tourism Growth
Looking ahead, 75% of respondents expect coastal and leisure tourism to be the primary driver of tourism demand growth in Egypt over the next five to ten years.
Cultural and heritage tourism ranked second at 64%, followed by business, meetings and exhibitions tourism at 36%.
Despite the strong outlook for cultural and heritage tourism, the report identified a gap between destinations expected to experience rising visitor demand and those currently attracting investment.
Only 3% of respondents selected Luxor, Aswan and the Nile Corridor as the most attractive destinations for hospitality investment.
According to the report, this reflects investors’ preference for destinations offering stronger development momentum, easier accessibility and greater opportunities for expansion, despite the considerable long-term potential of Egypt’s cultural and heritage tourism market.
Meanwhile, approximately 79% of respondents expressed confidence that the Egyptian market could absorb hotel projects currently under development without facing significant oversupply risks.
The remaining 21% expressed concerns about potential oversupply, particularly in specific destinations or hotel segments.
North Coast Tourism: Year-Round Demand and Air Connectivity Remain Key Challenges
The North Coast continues to strengthen its position as one of Egypt’s most promising hospitality investment destinations, supported by major investments and announcements of new tourism and real estate developments.
According to the report, 82% of respondents expressed optimism about the region’s future as a tourism and investment destination.
However, seasonality remains the biggest obstacle to transforming the North Coast into a year-round tourism destination, identified by 75% of respondents.
Weak air connectivity ranked second at 54%, while 21% highlighted financing challenges and infrastructure readiness.
Despite these obstacles, 57% of respondents expect the North Coast to become a year-round tourism destination within the next five years, with the percentage rising significantly to 96% within ten years.
Only 4% believe this transformation is unlikely under current conditions.
Choufany stressed that the region’s long-term success will depend not only on the scale of hotel and real estate investments but also on overcoming seasonal demand patterns, securing regular air services and completing the infrastructure required to sustain tourism activity throughout the year.
Air Connectivity and Workforce Development to Shape Hospitality Growth
The HVS report identified air connectivity and workforce development as two of the most important factors determining Egypt’s ability to achieve its tourism growth ambitions.
According to the survey, 54% of respondents believe that available air transport capacity remains insufficient to support the country’s tourism expansion targets.
Meanwhile, 75% identified employee training and skills development as the most important factors in improving hospitality service quality and operational performance.
Hotel brands and professional management ranked next at 39%, highlighting the importance of attracting international hospitality expertise and strengthening professional hotel management practices.
Hala Matar Choufany noted that air connectivity repeatedly emerged as a major challenge throughout the survey, affecting the North Coast’s ability to attract visitors, hotel performance and the infrastructure needed to accommodate growing tourist arrivals.
The findings underline the importance of expanding aviation capacity and investing in qualified hospitality professionals alongside the development of new hotels and tourism destinations.
Investors Call for Incentives and Faster Licensing Procedures
The report found that investors are looking for a comprehensive package of government reforms to improve Egypt’s hospitality investment climate and accelerate project implementation.
Investment incentives topped investors’ priorities at 43%, followed by airport infrastructure development at 39% and faster approval and licensing procedures at 36%.
Financing programmes, land allocation frameworks and international tourism marketing each received 32% of respondents’ preferences.
The report also highlighted several recurring demands raised by investors, including greater transparency in the investment environment, faster administrative procedures, simplified land allocation and licensing processes, easier repatriation of foreign currency profits and improved access to financing.
These priorities reflect the need for an integrated investment framework that supports project development, reduces administrative barriers and strengthens Egypt’s competitiveness in the regional and international hospitality markets.
Egypt’s 30 Million Tourist Target by 2030: 79% of Investors See It as Achievable
The HVS survey also examined investor confidence in Egypt’s target of welcoming approximately 30 million international tourists annually by 2030.
The findings revealed that 79% of respondents believe the target is achievable, while 11% consider it unlikely.
This positive outlook reflects confidence in Egypt’s tourism fundamentals and its ability to attract additional international visitors, while highlighting the importance of expanding airport capacity, improving transportation networks and strengthening the operational capabilities of the hospitality sector.
Achieving the target will also require continued investment in hotel infrastructure, workforce development and the diversification of tourism products across the country.
HVS Report: Turning Investor Confidence into Real Hospitality Projects Is the Next Challenge
The HVS Egypt Hospitality Investment Pulse 2026 report concluded that Egypt has largely succeeded in establishing investor confidence in the future of its tourism demand, supported by positive expectations for hotel performance and growing interest across several tourism destinations.
However, the main challenge in the coming years will be translating this confidence into actual investments and financially viable projects that are ready for implementation.
The report identified foreign exchange risks, financing availability, air connectivity, workforce development and regulatory efficiency as the key factors likely to determine the pace of hospitality sector growth.
It added that investors capable of managing these challenges and identifying opportunities beyond the most heavily targeted destinations could be better positioned to benefit from the next phase of tourism expansion in Egypt.
The survey included a broad range of hospitality industry stakeholders. Hotel and asset owners represented 45% of respondents, followed by developers at 29%, alongside representatives of financing institutions, investors, family offices and government entities.
The report clarified that its findings reflect the sentiment and expectations of survey participants rather than a statistically comprehensive representation of the entire market. It also noted that the research was conducted amid regional uncertainty, which should be considered when interpreting its indicators and projections.